All Categories
Featured
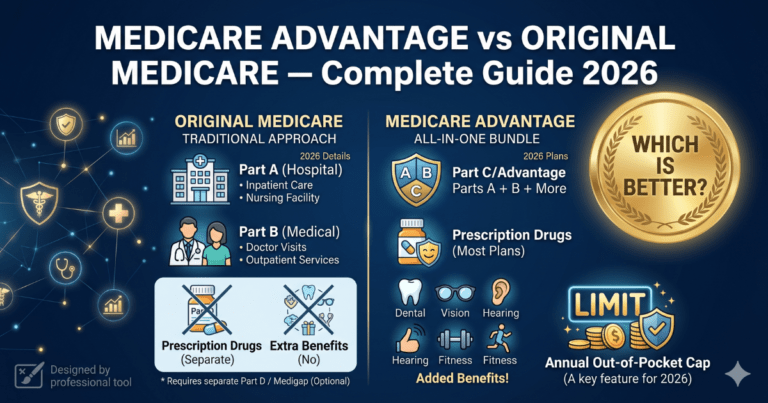
Direct Consumer Guide for Selecting 2026 Medicare Insurance
Understanding How Whole Life Insurance Secures Your Future

Essential Final Expense and Burial Insurance for Seniors
Table of Contents
Households select a CHIP carrier during enrollment, and the carrier manages all plan advantages, permissions, and client service. CHIP carriers are different from Pennie market carriers not all Pennie carriers participate in CHIP. How does the 2026 aid cliff affect Pennsylvania household health insurance? The return of the 400 percent FPL subsidy cliff in 2026 around $128,600 annual earnings for a household of four substantially increased costs for middle-income Pennsylvania households on Pennie.
Even households above the APTC threshold might have children eligible for CHIP if family earnings is below 319 percent FPL per-child, substantially lowering total household coverage cost. Can Pennsylvania households enroll in CHIP outside of open registration?
Kids who get eligibility due to income modifications, loss of other coverage, or other scenarios can be enrolled in CHIP at any point throughout the year. CHIP, Medical Support, and Pennie marketplace strategies typically collaborate for Pennsylvania families.'s certified PA brokers validate eligibility for every home member and complete registration at no extra cost.
is not affiliated with Pennie, the Pennsylvania Department of Human Services, the Pennsylvania Insurance Coverage Department, or any provider consisting of CHIP providers. The firm helps Pennsylvania residents compare plans and register in protection at no extra cost.
An insurance coverage program collectively moneyed by states and the federal government that offers health insurance coverage to low-income kids and, in some states, pregnant females in households who earn excessive earnings to qualify for Medicaid however can not afford to purchase private medical insurance coverage.
Finding Affordable Medicare Advantage Options
We learned the other day that the average cost of a household medical insurance policy through a company reached nearly $27,000 this year, 6% greater than what it cost in 2024. As if that weren't disconcerting enough, scientists are forecasting that the overall likely will soar toward $30,000 next year because of increasing medical costs and the unrelenting pressure insurers are under from Wall Street to increase their profits.
In spite of duplicated guarantees from insurers that we can rely on them to hold down the cost of health care and as a result the premiums they charge there are now several years of proof from researchers like KFF, which tracks yearly modifications in employer-sponsored coverage that they have not and can not provide on their promises.
A health insurance coverage policy today is usually less valuable than it was a years back since families have to invest more and more cash out of their own pockets every year before their protection starts. In addition, they are much more most likely to be notified that their insurers will not cover the care their medical professionals state they need.
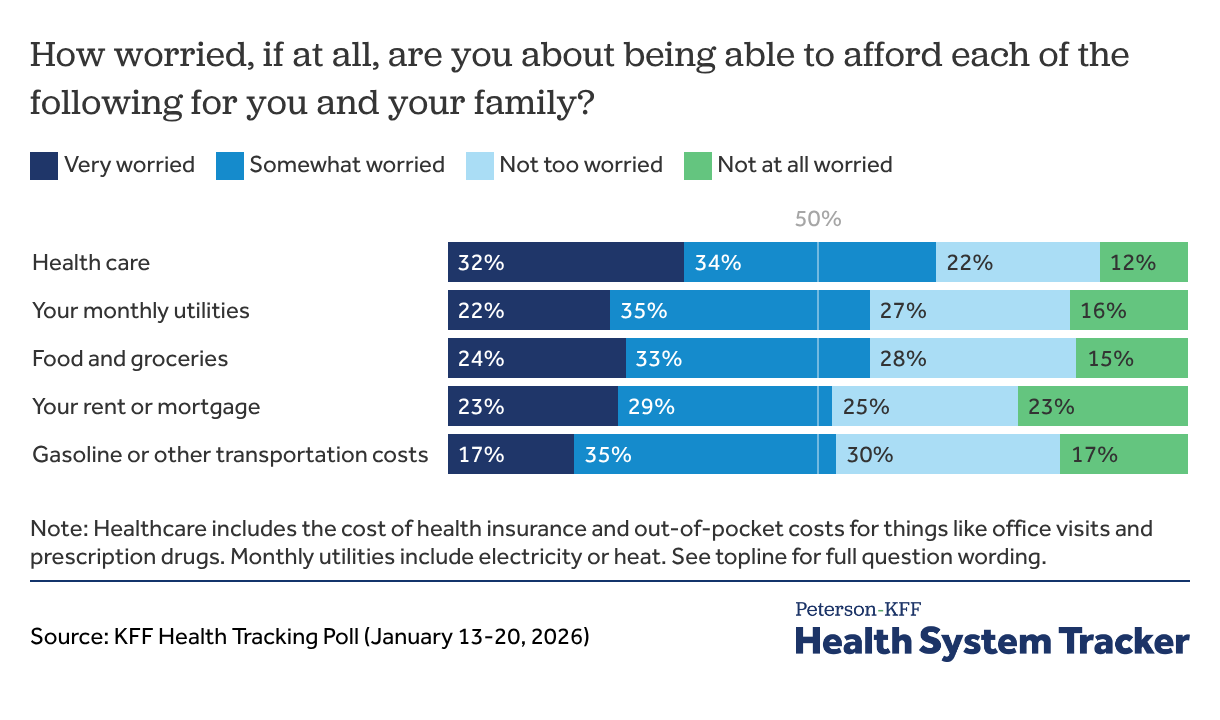
That is a rate of increase much higher than basic inflation and likewise greater than medical inflation. Not just has the overall cost of an employer-sponsored strategy skyrocketed, so has the share of premiums workers should pay. This year, employers deducted an average of $6,850 from their employees' paychecks for family coverage, up from $4,823 in 2014, a 42% increase.
Medicare Fraud Prevention ChecklistThe Affordable Care Act, to its credit, set up a cap on out-of-pocket expenses in 2014, however that cap has actually been increasing annually together with premiums. (The U.S. Department of Health & Human being Services sets the out-of-pocket max every year, pegging it to the typical boost in premiums.)In 2014 the out-of-pocket cap for a household policy was $12,700.
Reviewing New Life Insurance Rates for Veterans
And remember that the cap just uses to in-network care. If you head out of your insurance provider's network or take a medication not covered under your policy, you can be on the hook for hundreds or thousands more. While the majority of employer-sponsored strategies have caps that are substantially lower, many individuals and families reach the legal max every year.
Insurers said their 2024 earnings were somewhat depressed due to the fact that more of their health strategy enrollees went to the physician and chose up their prescriptions last year. Investors were furious that insurers couldn't keep that from occurring, as you'll see in the charts below.
Overall, the stock costs of the huge insurance coverage corporations have increased progressively over the years as we and our employers have actually had to spend more for policies that cover less. By contrast, the Dow Jones Industrial Average increased 139% (from $17,823.07 to $42,544.22), and the S&P 500 increased 186% (from $2,058.90 to $5,881.63) during the exact same duration.

Latest Posts
Reviewing New Life Insurance Benefits for Veterans
Understanding PPO Versus PPO Networks
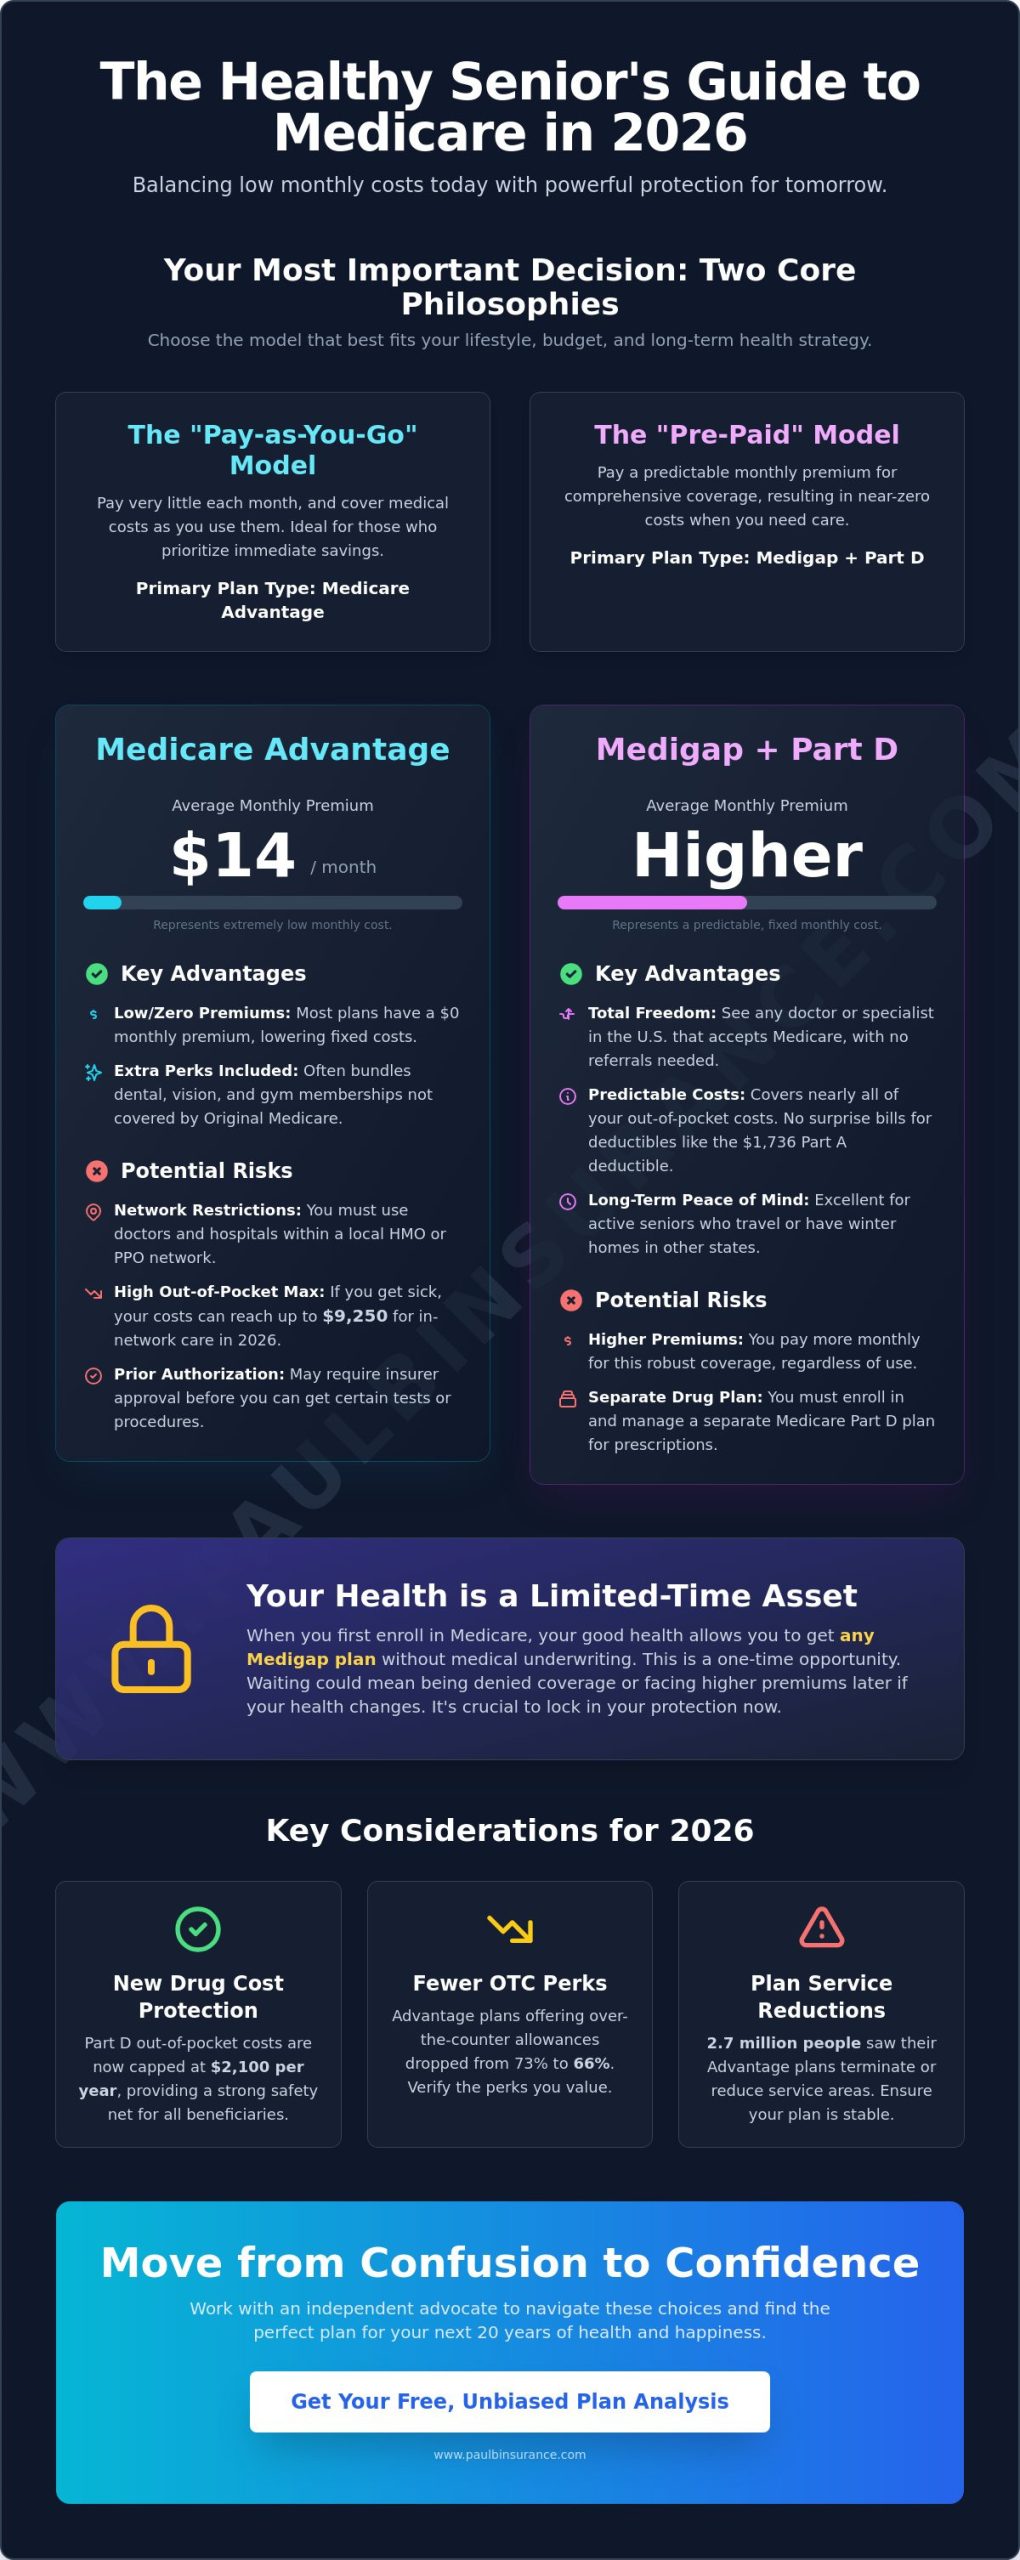
Direct Consumer Guide for Selecting 2026 Medicare Insurance